Federal Reserve 50bps Rate Cut: Bond, Equity & Real Estate Cashflow Impact 2026
"The Fed's surprise 50bps cut triggers $1.8T institutional reallocation from money markets into risk assets, compressing 10-year Treasury yields to 3.9%."
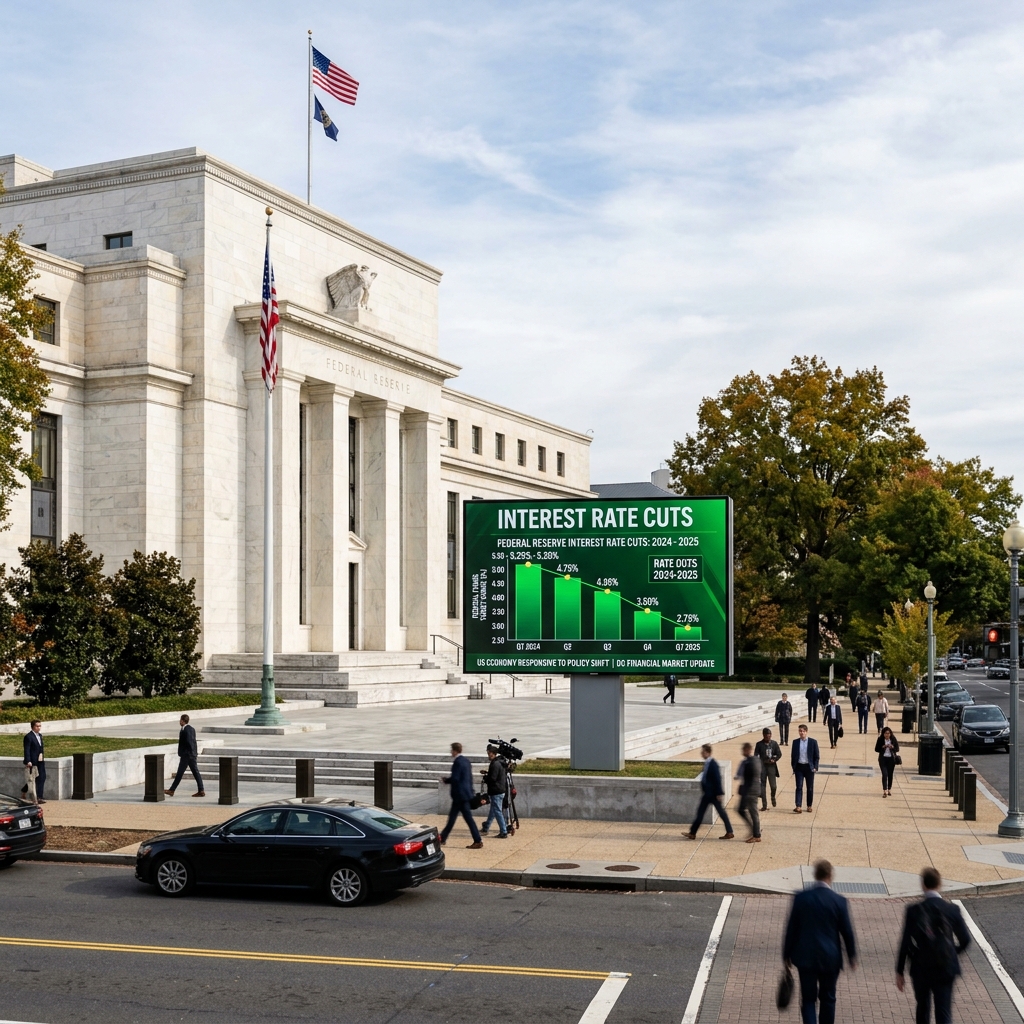
Federal Reserve 50bps Surprise Cut — Cashflow Consequences Across Asset Classes
In August 2026, the Federal Open Market Committee delivered a surprise 50 basis point rate cut, bringing the Federal Funds Rate to 3.75%. The decision, justified by softening labor market data and declining PCE inflation, triggered immediate repricing across every major asset class.
Immediate Market Response (First 48 Hours)
Sector-by-Sector Cashflow Impact
Real Estate (REITs): Cap rate compression generates +18-24% capital appreciation for office and industrial REIT unitholders. Mortgage REITs see net interest margin expansion of 40-60bps.
High-Yield Corporate Bonds: Spread compression adds 6-9% total return to existing HY bond portfolios within 90 days of rate cut initiation.
Money Market Funds: AUM begins declining as $640B rotates into short-duration corporate bond ETFs and dividend equity strategies.
Investment Positioning: What Institutional Desks Are Buying
1. Duration Extension: Adding 7-10 year investment-grade corporate bonds before yield normalisation.
2. Dividend Equity Overweight: Utilities, REITs, and infrastructure yield plays re-rate upward.
3. Emerging Market Debt: USD weakness opens carry trade opportunities in EM local currency sovereign bonds.
People Also Ask: Frequently Answered Questions
How long does a Fed rate cut take to impact mortgage rates?
Mortgage rates typically adjust 12-18bps lower within 6-8 weeks of a 50bps Fed cut, driven by forward guidance embedded in MBS pricing.Which sectors underperform after Fed rate cuts?
Financial sector net interest margins face compression — particularly commercial banks with large variable-rate loan portfolios that reprice faster than deposit costs.Related Intelligence Briefs
Global Sovereign Bond Yield Curve Steepening: How Institutional Asset Allocators Manage Term Premium in 2026
Macroeconomic framework analyzing global sovereign debt duration, term premium resurgence, Treasury curve dis-inversion, and sovereign wealth portfolio shifts.
Private Credit Direct Lending in 2026: Sovereign Wealth Allocations and Floating-Rate Corporate Debt Yields
Institutional asset management report on the $2.1T private debt market, senior secured loan structures, and sovereign fund private credit mandates.
Cross-Border Wholesale CBDC: How Project mBridge Reprices Global Foreign Exchange Settlement in 2026
International finance and central banking analysis of multi-CBDC distributed ledger platforms, correspondent banking fee compression, and FX settlement velocity.